

SpaceX’s long-awaited IPO filing finally arrived, and the numbers underneath the mythology are far more questionable than the valuation narrative suggests.
At a rumored valuation approaching $1.5 trillion to $2 trillion, the IPO would become one of the clearest stress tests yet for whether markets still reward “story stocks” regardless of fundamentals — or whether the AI bubble is finally running into the limits of valuation reality.
Based on the company’s S-1 filed yesterday and annualized first-quarter 2026 revenue, SpaceX could trade at well above 100x EV/revenue while growing sales only around 15% year-over-year if it achieves the valuation it wants.
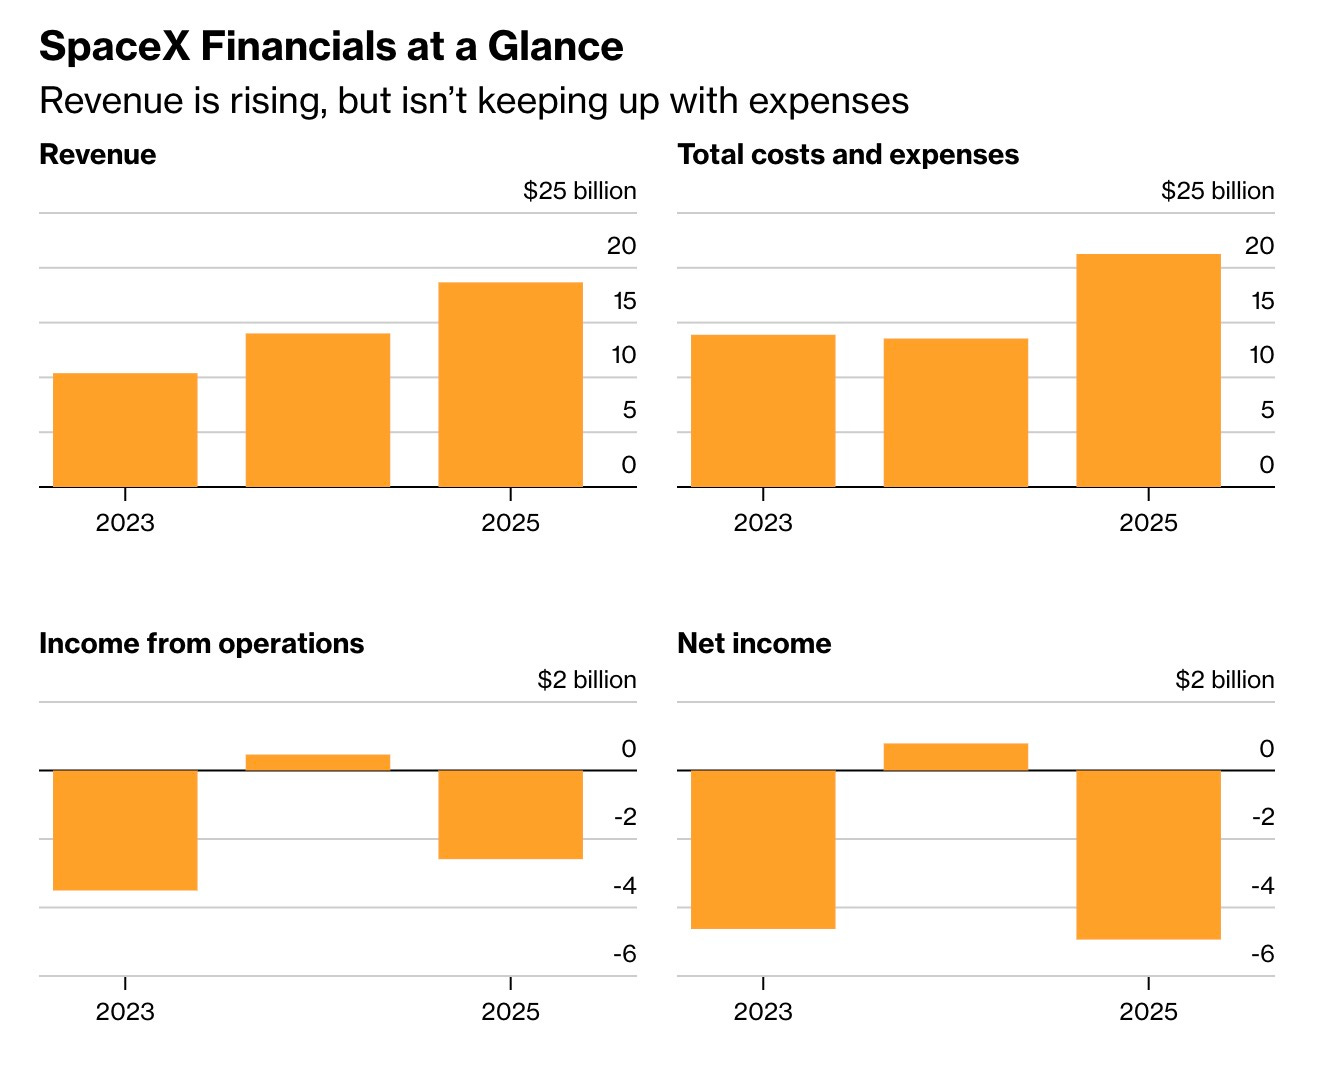
For context, that multiple is not merely rich by aerospace standards; it is extreme by virtually any public market standard. Investors would effectively be paying decades of optimistic future execution upfront for a company that is currently burning enormous amounts of cash and generating substantial operating losses.
The filing shows SpaceX burned roughly $5 billion in cash during 2024 and approximately $13 billion during 2025. Even more alarming, the company appears to have burned roughly $15 billion in the first quarter of 2026 alone as AI infrastructure spending accelerated following the xAI integration. It has just $15.8 billion in cash & equivalents, making me wonder what the company would be doing for cash if it wasn’t going public.
Some of the underlying financials are very difficult to reconcile with the valuation being floated: