

By Thomas Savidge, American Institute of Economic Research
I was only a few days into my role at AIER when Pete Earle penned “$34 Trillion and Climbing” in January 2024. Six months later, he published “$35 Trillion—and Counting” on July 31, 2024. Now, just two years and 18 days later, gross federal debt passed the $40 trillion mark on August 18, 2026. Although the debt held by the public (gross federal debt minus intragovernmental holdings) is “only” about $32.3 trillion, both measures indicate a clear warning: America’s fiscal institutions need serious reform.
Perhaps more concerning than the number itself is how little attention the milestone received outside those already interested in the subject. That indifference is perhaps unsurprising. For the average American, daily life appears (at least on the surface) to have changed relatively little, despite doomsday predictions that frequently accompany national debt headlines. Historic debt markers come and go, and somehow the sky has yet to fall and we all must still get up and go to work in the morning.
The rising debt nevertheless deserves attention, because the underlying fiscal trajectory threatens our standard of living and is compounding the affordability pressures Americans already face. Those who care about the national debt, however, should avoid the doomsday rhetoric. Every uneventful milestone we pass makes exaggerated warnings easier to dismiss and the case for serious reform harder to sustain.
Apocalypse Now?
Nothing economically decisive happened when the gross debt moved from $39.99 trillion to $40 trillion. There is no magic number at which the US suddenly becomes insolvent. The Congressional Budget Office has long acknowledged that no identifiable debt-to-GDP “tipping point” can reliably predict whether or when a fiscal crisis will occur.
Debunking an imminent catastrophe should not be confused with defending the status quo. The relevant question is whether current policy leaves the country more prosperous and financially capable a decade from now. CBO projects that debt held by the public will rise from 101 percent of GDP in 2026 to 120 percent in 2036, exceeding the postwar record. Over the same period, the annual federal deficit is projected to grow from $1.9 trillion to $3.1 trillion.
Those figures reflect a structural imbalance. Under current law, federal spending is projected to remain persistently higher than federal revenue. Economic growth may narrow that gap, but CBO does not project growth sufficient to close it.
This is a very different concern from imminent bankruptcy. A fiscal crisis might never arrive on a predictable schedule. The more probable danger is a gradual erosion of economic growth, household purchasing power, and the government’s freedom to respond to future challenges.
As Pete himself wrote back in the halcyon days of 2024 and a $34 trillion national debt, “Too much credibility has been squandered on the futile endeavor of predicting fiscal tipping points.” Instead, he recommends, and I concur, that the better strategy is explaining the effects of unsustainable debt on the average person.
What $40 Trillion Actually Means for You
The national debt did not single-handedly make housing, cars, groceries, or healthcare expensive. Prices and borrowing costs reflect monetary policy, relative price changes, and productivity among other factors.
Still, persistent federal borrowing can intensify affordability problems through several channels.
First, the federal government competes with private borrowers for capital. When the Treasury issues more debt, some savings that might otherwise finance homes or business expansion instead are crowded out to finance government spending. As Nobel Prize-winning economist James M. Buchanan stated, this is “in effect chopping up the apple trees for firewood, thereby reducing the yield of the orchard forever.” Greater federal borrowing can put upward pressure on interest rates, although it is only one of many forces affecting credit markets.
Recent events illustrate both the connection and its complexity. On August 19, the Treasury announced that it would at least double the size of its buybacks of 10- to 30-year securities, from $2 billion to $4 billion per operation. The announcement was followed by a decline in long-term Treasury yields, temporarily relieving some of the pressure that high government borrowing costs place on mortgages and other private credit.
The buybacks did not reduce the national debt because that was not the goal. They were intended to improve liquidity in parts of the Treasury market, but they may also complicate monetary policy. If Treasury actions push down long-term borrowing costs while the Federal Reserve is trying to restrain inflation, fiscal debt management and monetary policy can work at cross-purposes.
At the margin, higher government borrowing can make mortgages, car loans, and business credit more expensive. For families already struggling to purchase a home or replace a vehicle, even a modest increase in financing costs matters.
Second, weaker private investment can slow wage growth. Businesses increase worker productivity by investing in technology, properties, and employees. When less capital flows toward those investments, workers produce less than they otherwise would and their compensation grows more slowly. That cost is nearly impossible to observe directly. It appears as a business that does not expand, a job that is never created, or a raise that never materializes.
Third, persistent deficits can add inflationary pressure under some economic conditions. Debt does not automatically produce inflation, and $40 trillion does not mean hyperinflation is around the corner. It does, however, increase the temptation for Congress and the White House (regardless of which party is in power) to pressure the Fed to accommodate expansive fiscal policy by purchasing Treasury debt.
The debt’s clearest present cost, however, appears right in the federal budget. Net interest payments cost taxpayers more than $970 billion in fiscal year 2025. Put another way, for every dollar the federal government spent in FY 2025, 13.5 cents went to net interest payments. That’s more than defense spending (5.5 cents) or income security programs (12 cents).
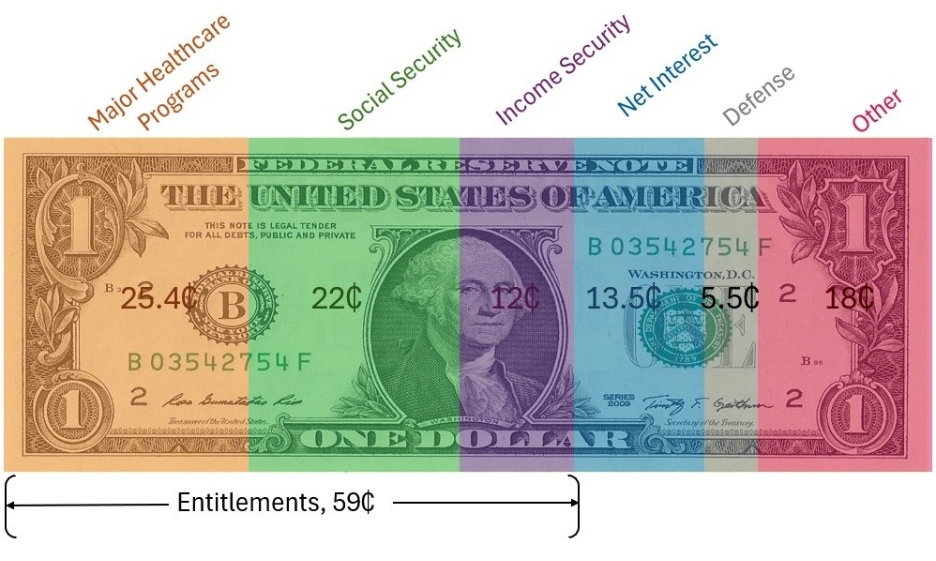
Those interest payments highlight a serious budgetary trade-off. A dollar spent servicing past debt cannot simultaneously finance an agency, reduce a tax, or prepare for the next emergency.
For the average American, that does not mean receiving a bill labeled “national debt.” It means future lawmakers will have less room to fund core services of government, reduce taxes, or respond to new priorities.
They will eventually have to choose between spending cuts, higher taxes, higher inflation, or some combination of the three. They arrive through a slightly more expensive mortgage, slower wage growth, higher taxes, or a weaker dollar. None resembles an apocalypse. Together, however, they can materially lower Americans’ living standards.
Pain Delayed Is Pain Multiplied
Government must be able to borrow during wars, recessions, and genuine emergencies. The problem becomes financing recurring regular commitments and structural deficits with debt.
The unprecedented level of debt does not automatically prevent the government from responding to another crisis, but it makes any response more expensive and adds to an already large net interest burden. Lawmakers and financial markets might also become less tolerant of aggressive emergency borrowing.
Fiscal space matters most when the country suddenly needs it. Using that space to finance routine deficits leaves less room for the unexpected.
Delay also changes who bears the cost. Current voters receive the benefits of government spending and tax reductions while future taxpayers, whether ourselves in the future or future generations, inherit the obligation to restore balance.
The longer policymakers wait to stabilize the debt, the larger the eventual tax increases and spending cuts must be. The consequences of delay will also fall disproportionately on younger and lower-income Americans.
Interest compounds financially and delays compound politically. Every year without reform creates new beneficiaries, new expectations, and new commitments. Policies that could have been adjusted gradually become more difficult to change.
Early reforms can be phased in while late reforms are more likely to be abrupt. They arrive when interest costs have already narrowed the available choices and when households have less time to prepare.
That is why the appropriate alternative to complacency is not panic-driven austerity. Sudden tax increases or indiscriminate spending cuts can result in disruption and political backlash. The goal should be a credible path that begins soon, proceeds at a steady pace, and stabilizes debt relative to the economy.
The longer reform is postponed, the more disruptive it is likely to become.
Toward a New American Fiscal Constitution
A new fiscal constitution means durable rules governing how government makes financial commitments, pays for them, departs from ordinary constraints during genuine emergencies, and then returns to them once the emergency subsides.
The status quo divorces those decisions. Congress authorizes spending and taxes first, then confronts the resulting borrowing through conflicts over the statutory debt ceiling. This limit, however, fails to control fiscal policy. Elected officials threatening to not raise the debt limit merely risks default, rather than affecting commitments already made.
An effective fiscal constitution starves the beast of both revenue and responsibility. Fiscal rules such as a Taxpayer Bill of Rights (TABOR), Swiss Debt Brake, or a BRAC-style commission for federal spending could help constrain how much a government taxes and spends. Limiting the government’s scope of authority helps prevent policymakers from finding workarounds to budget rules through regulation or accounting gimmicks.
Pessimism, however understandable, is unproductive. Americans went to work the morning after the debt crossed the $40 trillion mark. We will probably do the same when it reaches the current $41.1 trillion limit. The costs will instead emerge gradually through higher interest expenses, tighter budgets, weaker investment, and less capacity to respond to crises.
The danger is that every uneventful milestone will make the next trillion dollars seem normal. The sky does not need to fall for the debt to matter.

QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. This post represents my opinions only. In addition, please understand I am an idiot and often get things wrong and lose money. I may own or transact in any names mentioned in this piece at any time without warning. Contributor posts and aggregated posts have been hand selected by me, have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author, reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author. I cannot guarantee the accuracy of all facts and figures included in this article though I made my best effort to get them right. I have been wrong before and will be wrong again, and encourage you to always double check, do your own research and speak to a licensed financial professional.
This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions.
As of May 20, 2026 I am attempting to no longer actively trade as much as I once did (read my story here). My eventual goal is for investing/saving to be mostly done by recurring contributions mostly to sector ETFs and a few select equities, trusted third parties who oversee my accounts, and advisors. Such advisors or funds, through individual equities, options, index funds, mutual funds, ETFs, or other securities, may have positions in, exposure to, or holdings of names mentioned herein that I know nothing about. Basically, via index funds, ETFs and individual equities it is possible I could own, have exposure to, or not own anything at any point. As of the same date, May 20, 2026, in an attempt to lead a healthier lifestyle, I’ve also excluded myself from fantasy sports, sports betting, online and in-person casinos and prediction markets.
And all positions can change immediately as soon as I publish this, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier.
The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour. Also, I just straight up get shit wrong a lot. I mention it twice because it’s that important.
It’s the realization that this can never be pay back.
We can pay this debt. We can fix our deficit. Plans and ideas are not lacking (Ray Dalio's 3%). Political will is what we lack. Neither party will campaign and govern on fiscal austerity and higher taxes. Congress has forever been in the thrall of large donors to get elected. Worse, our elected officials use the offices we gave them to represent all constituents to enrich themselves front running stocks with their insider information. If each were ended people wouldn't want to be in office any longer than they had to. They would term limit themselves.