

Washington has a habit of changing its budget goals — not because the country solved the spending-driven debt problem, but because each goal proved harder than lawmakers were willing to confront.
I remember working on fiscal policy in 2011, when lawmakers still talked about balancing the budget. It was an intuitive target. If the government only spent what it collected in revenues, the debt problem would eventually disappear.
Simple in theory. Difficult to achieve in practice.
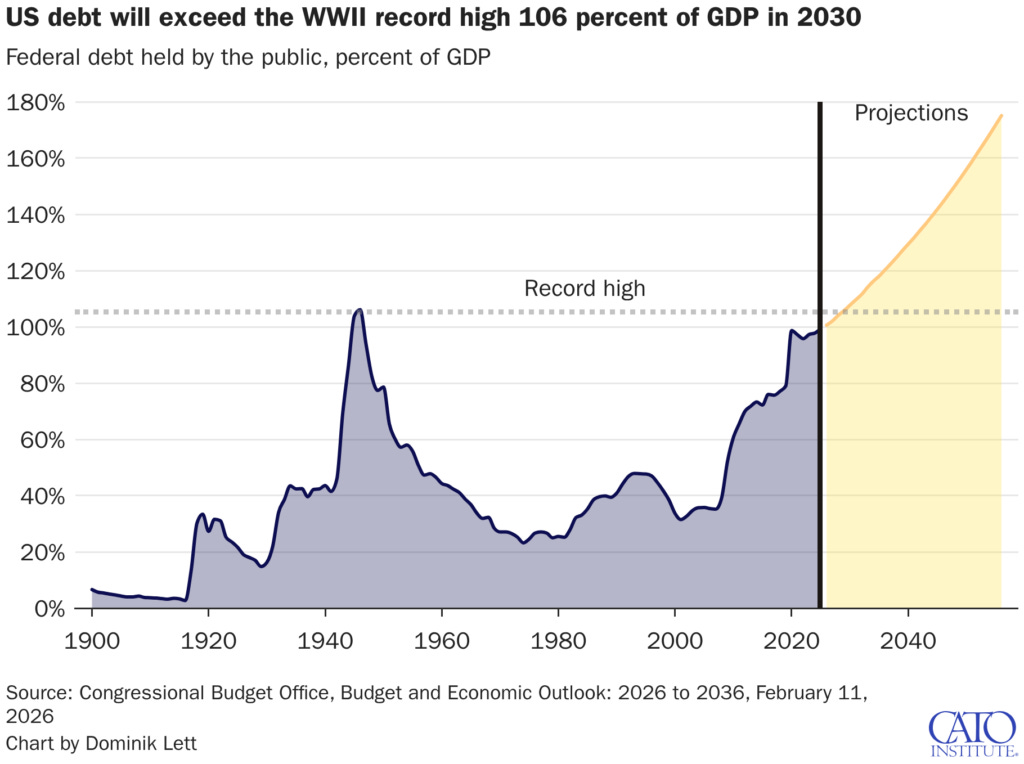
So the focus shifted to stabilizing the debt. When debt began approaching 100 percent of GDP in 2020 — as spending kept climbing and interest costs began growing steeply — balancing the budget looked increasingly unattainable.
Republicans kept up appearances for a while longer, inflating economic growth expectations in their budget plans to make up for a lack of fiscal restraint. If you can’t balance the budget honestly, maybe you can fake it? At least they tried to make the numbers work, albeit by invoking fiscal fantasies.
Now there is a new goalpost: limiting deficits to three percent of GDP. As House Budget Committee Chairman Jody Arrington (R-TX) recently stated on CNBC’s Squawk Box, following a congressional hearing to discuss the new target:
We’ve been looking at 10-year balanced budgets for decades. And we haven’t had a balanced budget in a quarter of a century. Today, if we’re going to balance in 10 years — that’s $18 trillion. We’d have to do what we did in the Big Beautiful Bill every year for 10 years.
So, I think any successful endeavor starts with defining success and setting achievable — ambitious — but achievable goals.
And in this case, we’re talking about reframing where we take our crisis level annual deficits per economic output, which is about six percent of GDP, and put it on a glide slope down to three percent — here we’re growing the economy faster than our rate of deficit spending and inflation. That should put us on a better trajectory, a more sustainable one. And then, we can take it from there on a more ideal path to balance.
Arrington is right that setting an achievable goal matters. We should also be clear about what this new goal represents.
A deficit-to-GDP target is no more — or less — arbitrary than any other fiscal benchmark short of balance. There is nothing inherently magical about three percent. It is not a law of economics. It is a political and analytical compromise.
For years, New Keynesian economists have argued that governments do not need to balance their budgets, only to keep deficits at a level consistent with a stable, or even slowly rising, debt burden, so long as the interest rate on public debt remains below the economic growth rate. This politically convenient argument was lauded in academic and government circles. How swell to have cover to continue growing the debt burden on younger generations because “the economists” said it was OK to do so.
But “sustainable” was never meant to suggest “unlimited.”
In that sense, the three percent target may be more honest than what came before. It acknowledges that the United States is not on a path to balance anytime soon and sets a minimum condition for avoiding further deterioration.
This is important if we can finally achieve bipartisan recognition that current deficits — growing from six percent of GDP to nine percent annually over the next few decades — are unsustainable. As discussed in the recent House Budget Committee hearing, reducing deficits to three percent of GDP would roughly stabilize the debt at today’s already elevated levels. It could stop the debt from growing even bigger as a share of the economy. That’s critical.
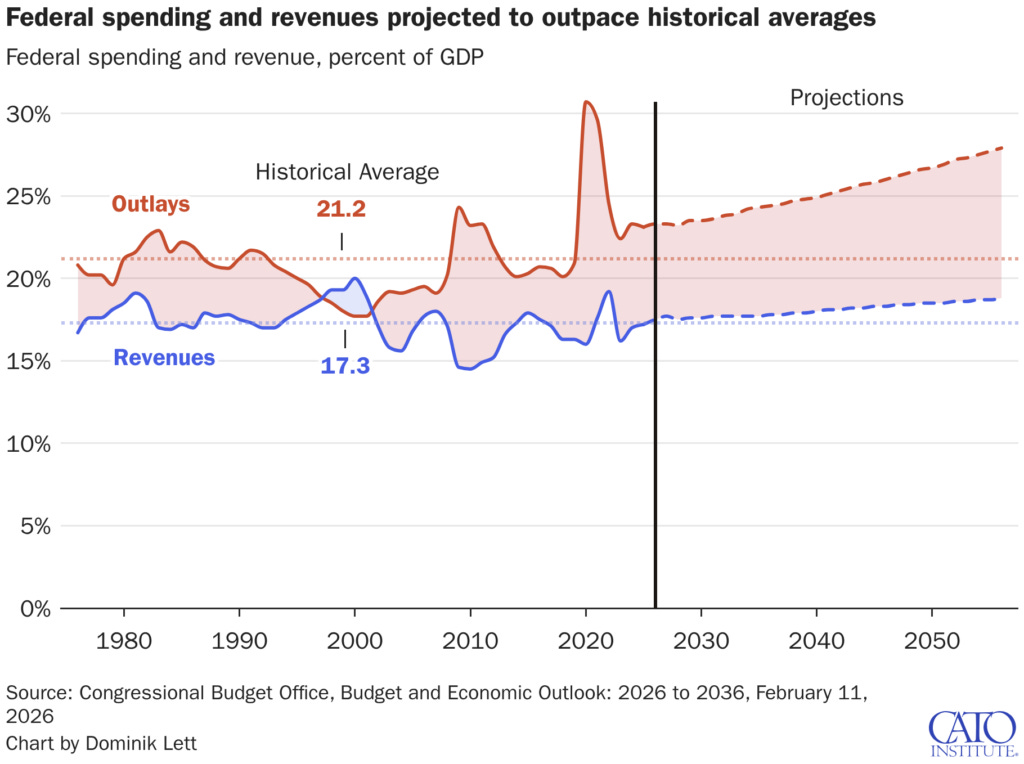
And yet even this goal demands far more political will than Congress has demonstrated. The scale of the adjustment is significant. Bringing deficits down to three percent of GDP would require roughly $10 trillion in deficit reduction over the next decade.
That is the real test. Can Congress agree on a target and make the necessary fiscal adjustments to achieve it?
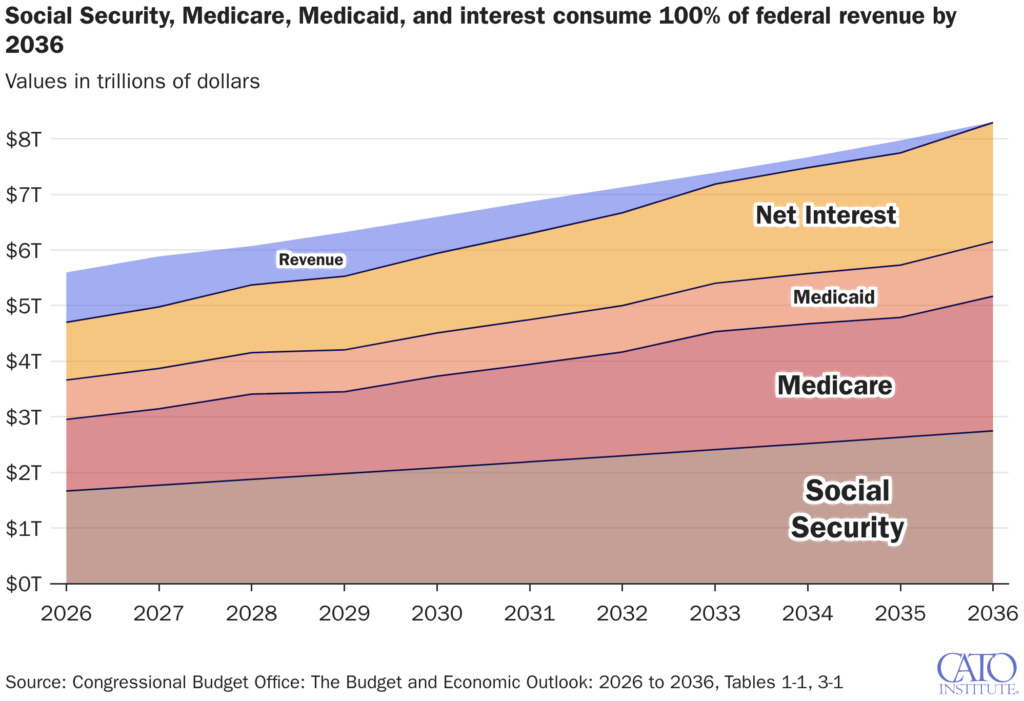
Because the urgency to rein in the growth of US debt is no longer abstract. The United States has now been downgraded by all three major credit rating agencies. Interest costs are rising rapidly and already rival spending on national defense. Looking ahead, the federal government’s largest obligations — Social Security, Medicare, Medicaid, and interest on the debt — are projected to consume all federal revenues within little more than a decade. At that point, every other government function — from national defense to infrastructure to basic operations — would have to be financed with borrowed money.
Something has to give. And that is where Congress consistently falls short.
Most federal spending operates on autopilot. Mandatory programs — primarily Social Security, Medicare, and Medicaid — make up the bulk of the budget and are rarely revisited in any comprehensive way. Lawmakers barely even debate discretionary spending anymore, and Republicans have increasingly turned to mandatory spending to fund portions of defense and immigration enforcement.
Following the deficit-increasing One Big Beautiful Bill Act from July 2025, Congress is again considering budget reconciliation — this time in part to finance additional military spending related to the conflict with Iran and to circumvent Democratic opposition to funding ICE.
Reconciliation could provide an opportunity to enact broader fiscal reforms, including reducing spending on major entitlement programs. The growth in Medicaid and food stamp spending, for example, was slowed in the latest reconciliation bill, in part framed as an effort to reduce waste, fraud, and abuse. Those are legitimate concerns. Yet even eliminating fraud would not come close to arresting the growth in spending and debt.
Without significant changes to health care programs and Social Security — the largest drivers of rising government debt — the pattern will repeat. Congress will announce targets, defer them, and eventually replace them.
Congress does not lack warnings. Interest costs are rising, debt is growing faster than the economy, and fiscal space is shrinking. The question is whether lawmakers will treat the three percent target as a turning point — or as the next step in lowering expectations.

QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. This post represents my opinions only. In addition, please understand I am an idiot and often get things wrong and lose money. I may own or transact in any names mentioned in this piece at any time without warning. Contributor posts and aggregated posts have been hand selected by me, have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author, reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author.
This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions. All positions can change immediately as soon as I publish this, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier.
The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour. Also, I just straight up get shit wrong a lot. I mention it twice because it’s that important.
The popularity of tax cuts and the rising needs of SS, Medicare, etc. have created a perfect storm in which now the boat is half sunk and still no one wants to start bailing water. We don't have the demographics or manufacturing base, or willingness to reduce red tape to grow ourselves out of it like we did post WWII. Can we fix SS by treating it more like a pension fund with a broader base of portfolio components? Can Medicare be fixed by having a Medicare for All umbrella that delivers volume price reduction across the board? Eventually we're going to have to figure this out, and ironically funding the budget may be the only thing Democrats and Republicans will actually have in common.
The huge debt in the 1940s was for funding WWII. Not just our own costs, but after the war the USA largely ultimately funded much of the allies' costs, and probably a fair amount of Axis costs. Yet the USA paid down the debt in relatively short order.
We see an equivalent debt today, with no excusable reason for its existence, and no real plan to do anything about it. We are stealing from our children. Running up the credit card and handing them the bill.
In the 1980s Chrysler was going broke, hemorrhaging money. Their solution? keep manufacturing cars that customers weren't buying. Why? Because that's what they'd always done it before, and it hadn't occurred to anyone to make changes. Lee Iacocca came in and made the necessary changes, for awhile anyway.