

By Thorsten Polleit, Mises Institute
On April 14, 1912, at 11:40 pm, the Titanic—the legendary passenger ship regarded as unsinkable—tore open its hull on an iceberg during its maiden voyage from Southampton to New York. The watertight compartments filled with water, and—just 2 hours and 40 minutes later—the ship sank in the icy waters of the North Atlantic. Approximately 1,517 people lost their lives—not least because the Titanic did not carry enough lifeboats and the crew failed to summon help by radio in time.
To stay with the metaphor: Just as the iceberg collision ultimately led to the Titanic’s demise, a continued rise in interest rates can plunge the global financial and economic system into severe distress and, in the extreme case, trigger a fatal collapse, the going under, of the world’s financial and economic system. Let us call this the “Titanic Effect.”
Since 2020, interest rates have been climbing more or less steadily. The yield on 10-year US Treasuries, for example, has risen from 0.65 percent to currently around 4.5 percent. Yet the interest rate increase now appears to have taken on a momentum of its own. It has become more than just a “normalization” that merely lifts rates from extremely low levels back to historically more normal heights.
On the credit markets, doubts about the credit quality of many debtors are spreading, especially regarding government borrowers. This is hardly surprising given the enormous mountains of debt that governments—often enthusiastically encouraged by their voters—have piled up over recent decades. Living on credit was relatively easy because interest rates kept falling.
This long-term decline in interest rates was primarily the work of central banks under their fiat money regimes. In close cooperation with commercial banks, they continuously expand the money supply through bank credit creation. This allows not only consumers and producers, but especially governments, to finance their spending on a massive scale with credit at low cost.
Rising interest rates are now putting an end to this. They are causing interest payments to explode—and that is a huge problem. After all, governments typically do not repay their maturing debts on a net basis. Instead, they replace maturing debt with new debt—a strategy that works well as long as interest rates keep falling.
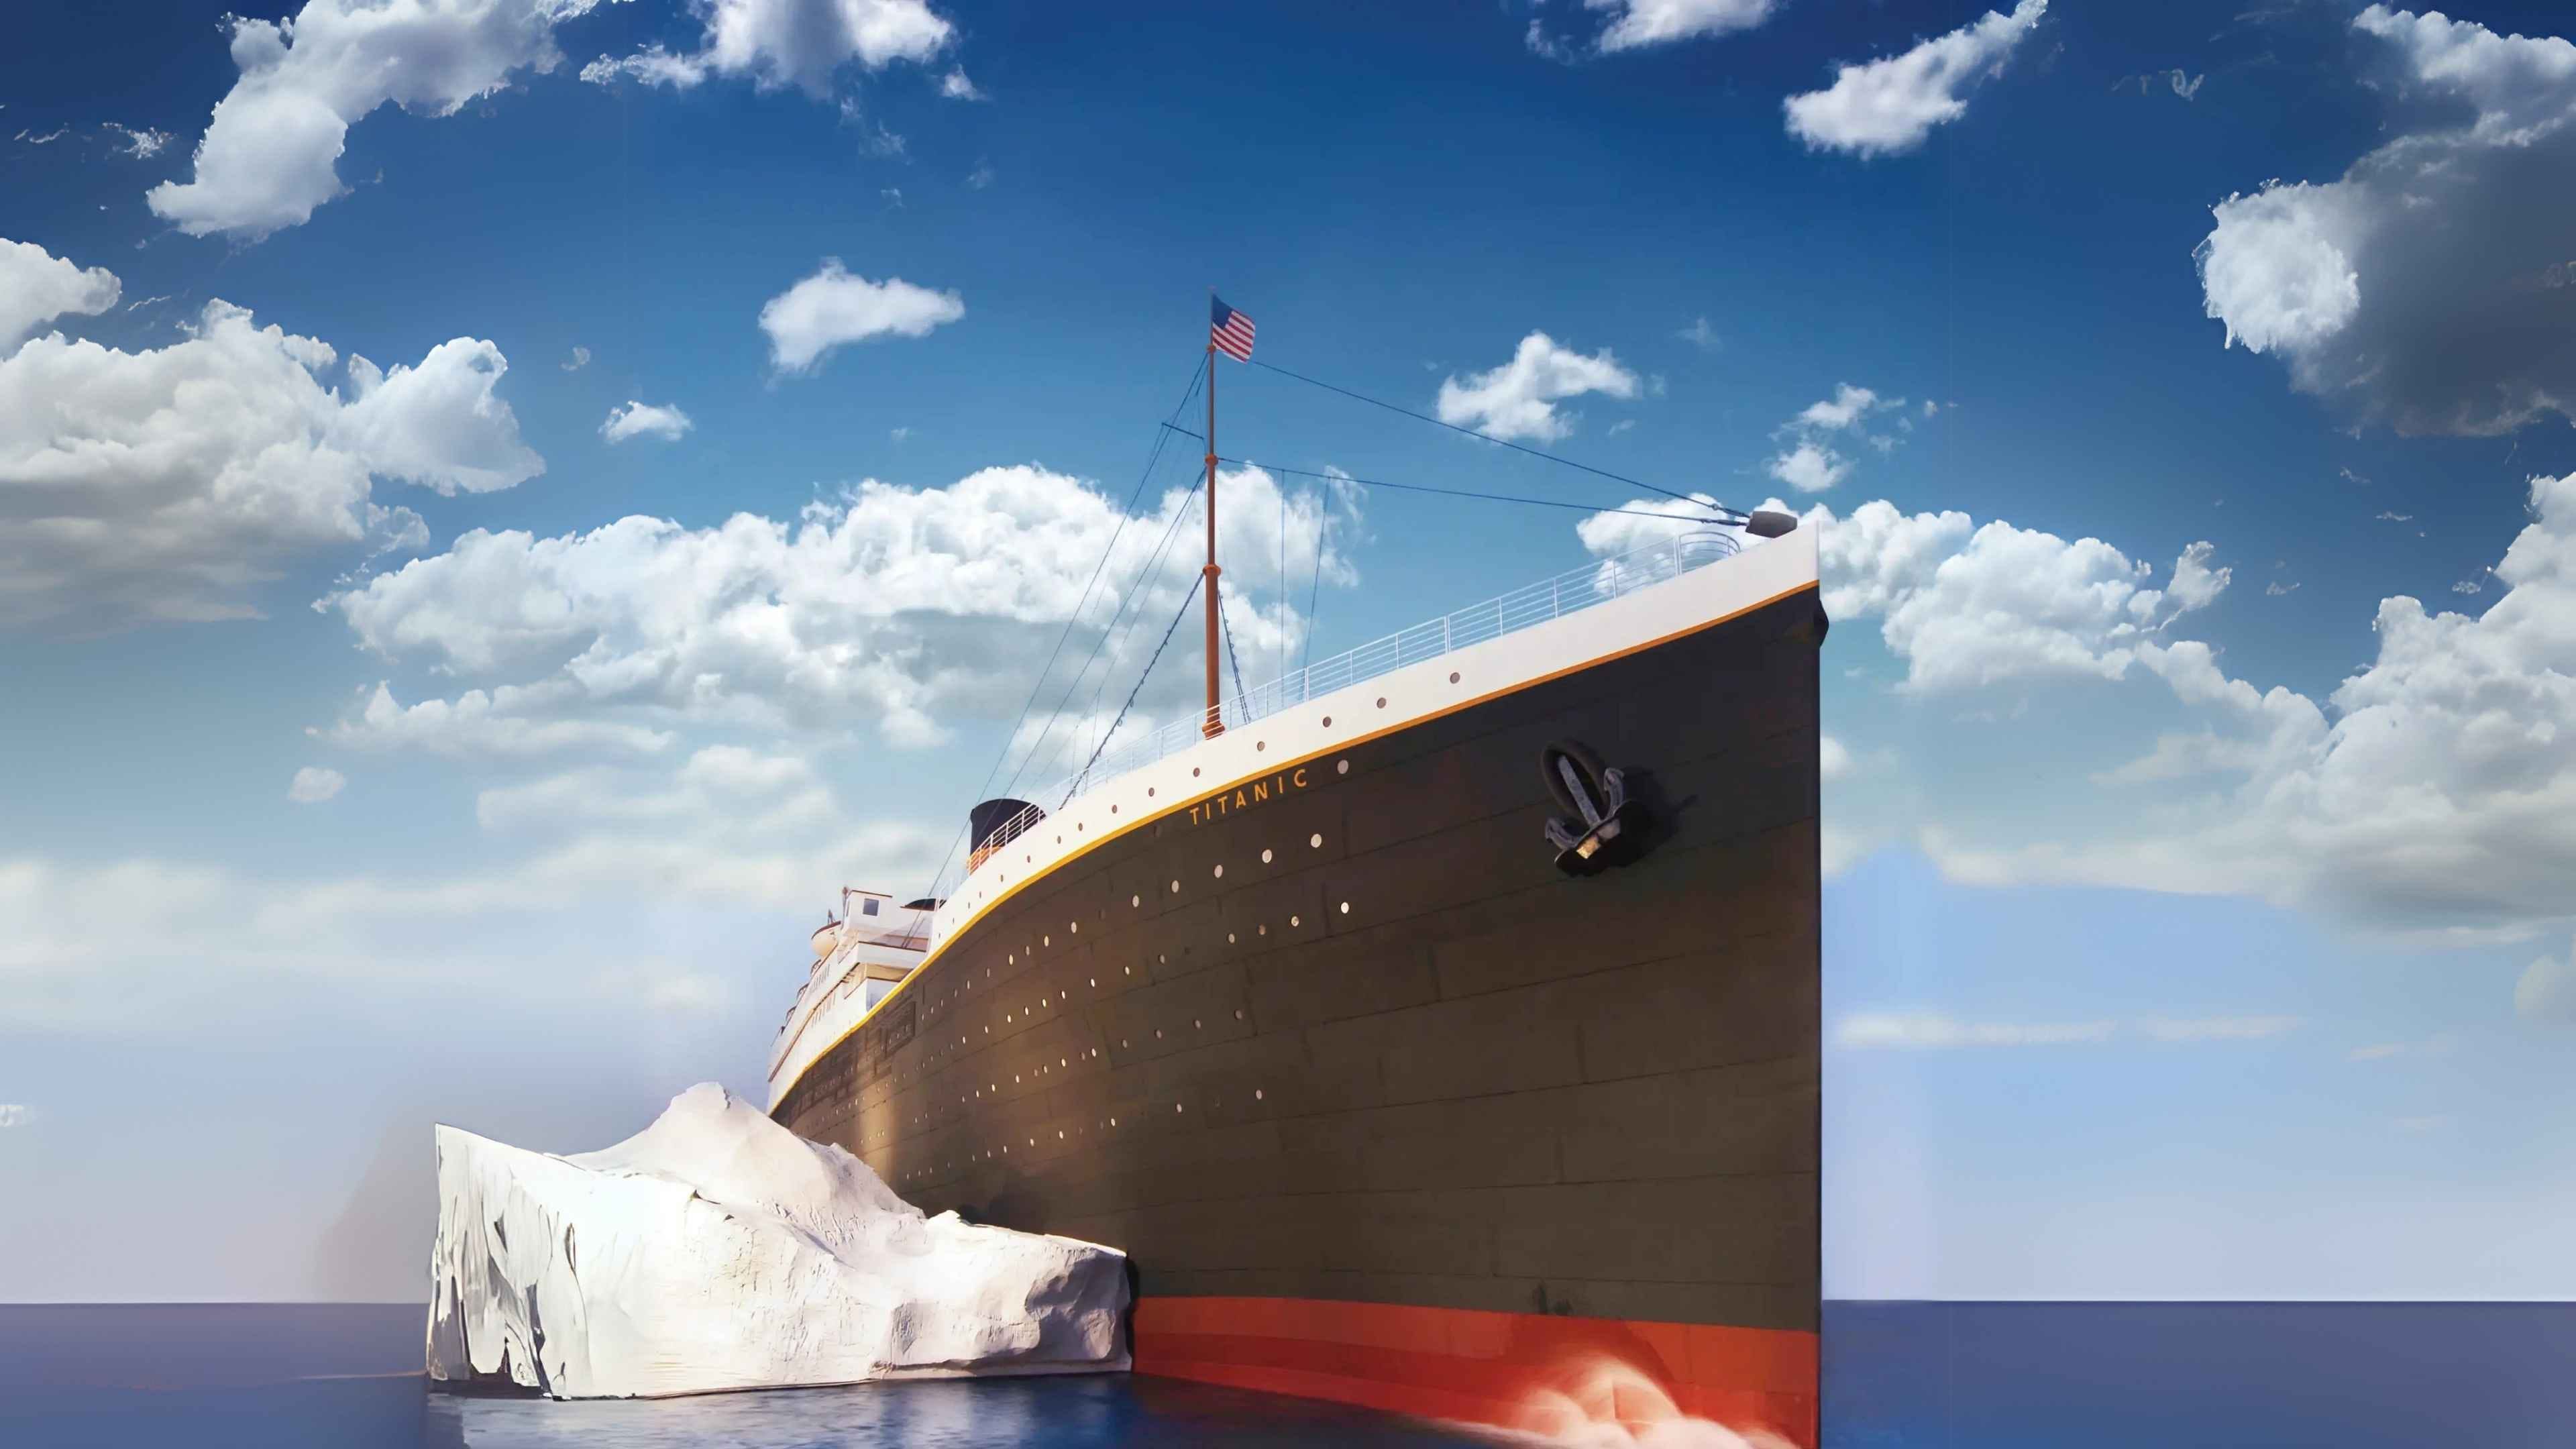
In an over-indebted fiat money system, however, rising interest rates are, to continue the metaphor, like a gash in the ship’s hull through which water floods in: The interest burden on outstanding debt keeps rising because maturing loans that are not repaid must be refinanced with new loans carrying higher interest rates. On top of that, new debt is constantly being added.
Take the United States of America as an example. In mid-2020, the US government’s annual interest bill stood at $508 billion, and, by the first quarter of 2026, it had climbed to $1,219 billion. Back then, total debt was $26.4 trillion; today it stands at around $39 trillion. The average refinancing rate is currently 3.1 percent. If it were to rise permanently to 4.5 percent, Americans would have to pay nearly $1.8 trillion in interest every year.
The interest burden already amounts to 3.8 percent of GDP—significantly higher than average economic growth. At a 4.5 percent interest rate, it would rise to a staggering 5.8 percent. The situation looks similar or even worse in many other economies—think of Japan, France, Italy, the United Kingdom, or Germany.
You don’t need to be a rocket scientist to realize that this cannot be sustained indefinitely. It is like water pouring into the hull: if the inflow is not stopped, the ship will eventually sink—not immediately, but gradually and inexorably. So what should investors expect?
Finding an answer to this question is probably not as difficult as it might first seem, because developments in the credit market are, to a large extent, pre-determined. Market interest rates have long been politicized by central banks. And there is no doubt that central bankers can fully control market interest rates at any time if it is politically desired.
So far, however, central bankers have not fully used their power over interest rates. They have allowed capital market rates to climb higher in recent years, presumably viewing this as a kind of “interest rate normalization.”
Yet, as already noted, further rising interest rates will steer the fiat money system into extremely dangerous waters. They could even cause the global debt pyramid to collapse. Rising rates worsen the debt-servicing capacity of many borrowers—which, in turn, drives refinancing costs even higher. A vicious downward spiral begins (that is, more and more water floods into the hull).

Not only the economy, but especially asset markets come under increasing pressure when interest rates continue to rise or remain high. Many investments no longer make economic sense, companies go bankrupt, and jobs are lost. Rising interest rates also push down the prices of stocks, real estate, land, and commodities.
It is therefore highly likely that central bankers will intervene in the credit markets once interest rates become too high and politically unsustainable. For example, by buying government bonds and paying for them with newly-created money. The consequence will be an expansion of the money supply and, sooner or later, rising goods prices across the board.
What does it mean for the investor? Here are four important conclusions:
The investor faces the challenge of protecting his capital from currency debasement. Inflation (broad-based increases in goods prices) remains the greater risk for him going forward than deflation (a continued broad-based decline in goods prices).
The investor must achieve a positive real interest rate after taxes—and this is crucial to understand. Only then can he escape inflation; a positive real return after taxes is also the only way for the investor to actually grow his capital.
Positive real returns after taxes can no longer be achieved with savings accounts, money market funds, or government bonds. What remains is, for example, the stock market. However, it is very important to note: The investor must ensure he does not buy stocks at inflated prices—otherwise he risks failing to achieve the necessary real return (after taxes).
The investor should (continue to) hold a portion of his portfolio in gold and silver. Even though precious metal prices are currently undergoing a correction, there are good reasons to expect the long-term upward trend in gold and precious metals to resume soon. Gold and silver serve as insurance with upside potential for the investment portfolio—they are, so to speak, the lifeboats that are indispensable for investors in a fiat money regime now experiencing a “Titanic Effect” (where it is unclear how much longer the ship’s compartments will continue to fill with water).

QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. This post represents my opinions only. In addition, please understand I am an idiot and often get things wrong and lose money. I may own or transact in any names mentioned in this piece at any time without warning. Contributor posts and aggregated posts have been hand selected by me, have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author, reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author.
This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions.
As of May 20, 2026 I personally no longer actively trade (read my story here). My investing/saving is done by recurring contributions mostly to sector ETFs and a few select equities, trusted third parties who oversee my accounts, and advisors. Such advisors or funds, through individual equities, options, index funds, mutual funds, ETFs, or other securities, may have positions in, exposure to, or holdings of names mentioned herein that I know nothing about. Basically, via index funds, ETFs and individual equities it is possible I could own, have exposure to, or not own anything at any point. As of the same date, May 20, 2026, in an attempt to lead a healthier lifestyle, I’ve also excluded myself from fantasy sports, sports betting, online and in-person casinos and prediction markets.
And all positions can change immediately as soon as I publish this, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier.
The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour. Also, I just straight up get shit wrong a lot. I mention it twice because it’s that important.
Too bad that GNP cannot be converted to pay off the interest expense. Like for gold and silver, these rate fluctuations are very long term...over many years or even decades. Never fear, the US taxpayers stand ready to bail out the country once again if need be. The DC Cesspool will see to that.
Great analysis. We face a monstrous risk, but gold and silver are not enough to save us. The solution is too timid.