

American citizens, the Fed, and bond markets all know: Inflation isn’t under control.
When the Fed prints, they write inflation on the wall. And even if they do everything “perfectly” to return inflation to the target of 2%, that’s just slowing down the pace of their stealing. Your purchasing power is still robbed from you, but it happens at a slower rate so that you don’t notice. But as the Fed normalizes incrementally more extreme “emergency” measures, like 2008 stealth bailouts, massive QE, and Covid-era money printing, they make their own 2% target number impossible to achieve and maintain.
Americans have felt it for a long time, but the frog continues to boil. Life keeps becoming less affordable, and even as the Fed knows that growth is weak and inflation isn’t going away, its answer to reducing “inflationary pressures” can only even be more of the same monetary policies that got us here.
All that anyone has to do is look at their grocery bill, gas receipt, or insurance payment, and compare to the same bills pre-Covid. The Fed has been forced to admit that inflation hasn’t gone away. And despite their affection for silly euphemisms like “transitory” when they think they’ve beaten inflation to “sticky” when they realize their solutions didn’t fix anything, the Fed is eventually always forced to acknowledge the failures of their monetary policy.
Now, the Fed is considering the interest rate question as markets wait and listen. There is by no means a conclusive answer on which way the Fed will go. But without aggressive rate hikes, inflation could head for double digits, because the Fed will remain trapped by enormous debt levels that make serious tightening politically and financially explosive.
Meanwhile, Russia banned diesel exports to head off domestic shortages after Ukrainian drone attacks hammered its refineries. That cuts off over 10% percent of global supply and slams already tight markets strained by Middle East conflicts. Diesel margins have shattered records, disconnected from crude prices, and will ripple straight into trucking, farming, and manufacturing costs.

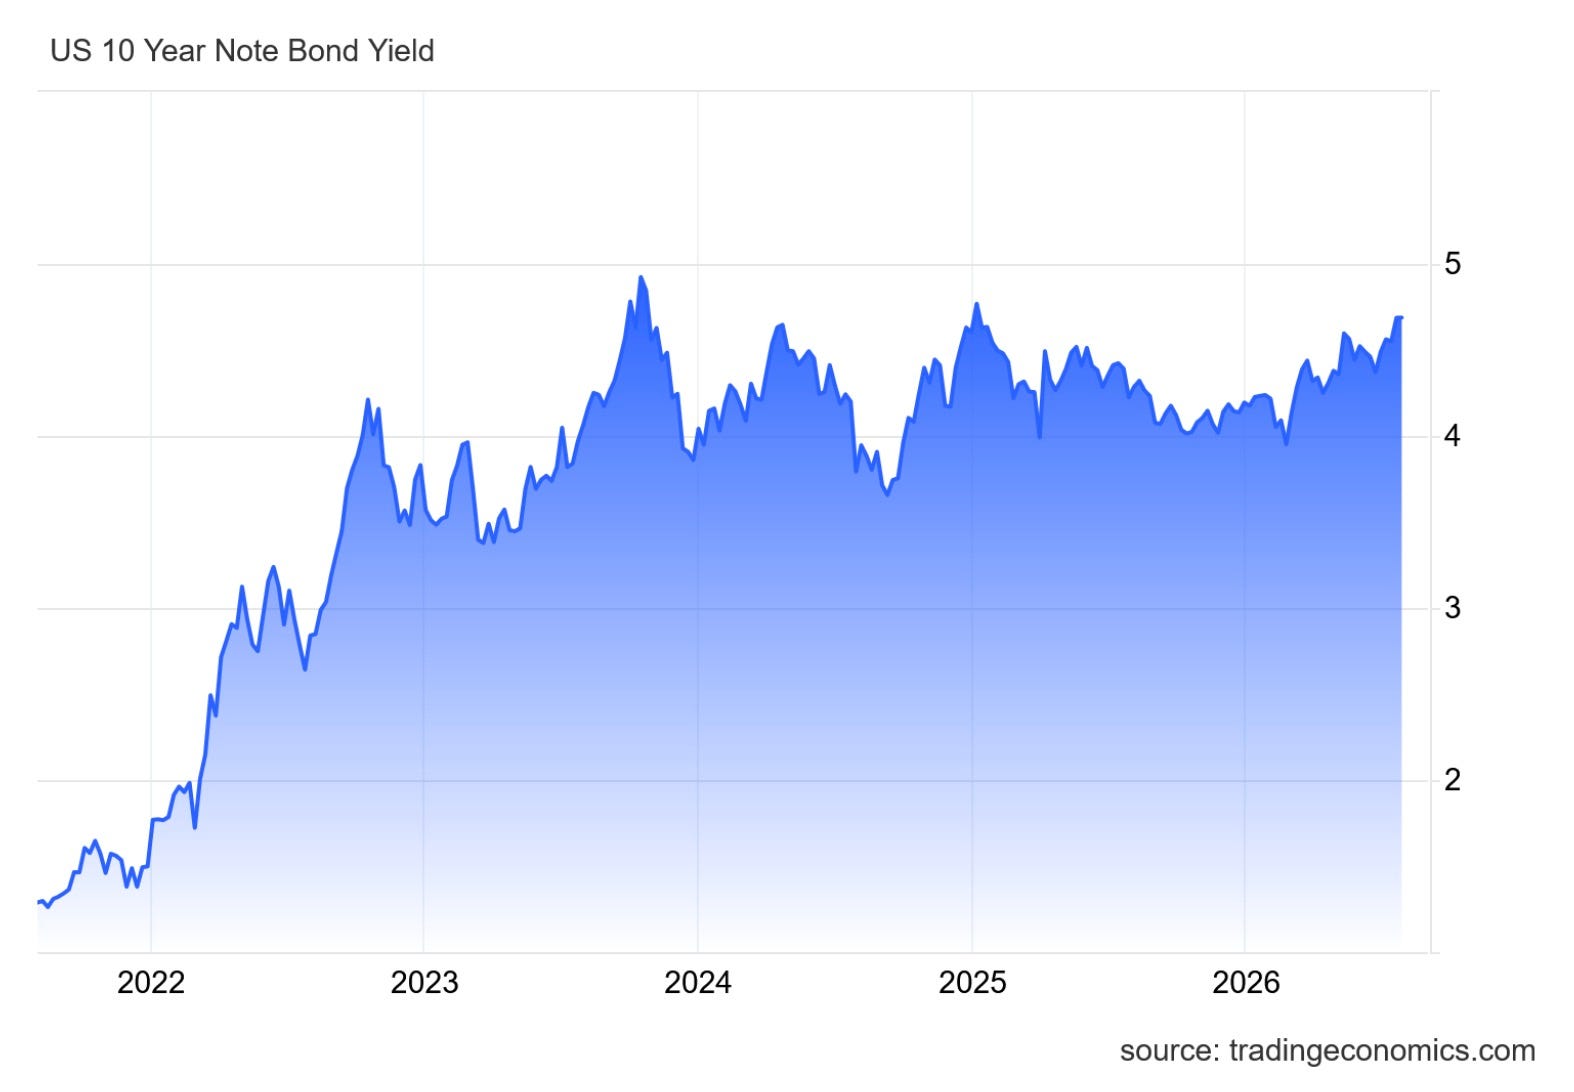
The bond market, where trillions of dollars are wagered every day on future inflation, growth, and interest rates, is sending the same message. Longer-term Treasury yields have climbed as investors demand greater compensation for the risk that inflation remains elevated for years to come. Bond investors aren’t listening to the Fed’s reassuring rhetoric about inflation returning neatly to target. They’re demanding a higher inflation premium because they increasingly doubt that outcome.
The bond market doesn’t respond to political speeches or optimistic forecasts. It prices probabilities with real money. When investors insist on higher yields despite slowing economic growth, they’re implicitly saying that inflation has become a more durable threat than the Fed anticipated. In other words, the market is beginning to price in exactly what American households have already experienced: higher prices are a long-term, structural consequence of years of monetary expansion, chronic deficits, and a central bank that cannot tighten policy enough without threatening the financial system itself.
These factors can compound years of massive deficits and monetary expansion that erode the dollar’s purchasing power. Without aggressive rate hikes, inflation heads for double digits because the Fed remains backed into a corner by enormous debt levels that make serious tightening politically and financially explosive.
“The 30-year Treasury yield is above 5.2% for the first time in twenty years. Warsh is afraid to raise rates due to the adverse consequences for markets & the economy. But his failure to raise rates will have similar consequences. We’re damned if he does and damned if he doesn’t.
The solution, of course, is always even more policy, as if no amount of seesawing back and forth could ever teach them that inflation is not something that an Ivy-league magician can conjure or exile with the wave of a wand. Expanding the money supply never magically creates real growth; it just bids up existing assets and necessities. Real economic growth will never be powerful enough under the current paradigm to prevent higher prices from monetary expansion.
Recent FOMC minutes make the Committee’s current opinion on inflation clear: It’s more persistent than they expected. They have a strong tendency to underestimate inflation until after the fact because they don’t want to admit the incredible hubris that is implicit in trying to control it. This time, of course, rather than their own tinkering, they blame the resilient demand driven by AI infrastructure investment, continued geopolitical tensions in the Middle East as Trump resumes his war in Iran, and the inflationary effects of tariffs. These can amplify price increases and economic instability, but the root cause of inflation is money printing.
Bond selloffs following renewed inflation fears and geopolitical tensions weren’t random volatility. They reflected investors repricing inflation risk and questioning whether the Fed will be able to deliver the low-inflation environment it continues to promise. Even periods of unusually subdued bond-market volatility should not be mistaken for confidence. Historically, stretches of calm in the Treasury market have often preceded sharp repricings when inflation expectations abruptly shift. Markets can ignore inflation for a while, but they cannot ignore it forever.
Most at the Fed agreed that further policy tightening could become necessary. And while it’s true that interest rates should be higher, the Fed will never go far enough. Even if they somehow perfected all their calculations and raised interest rates just as high as the free market would, the core problem would remain:
No human being can (or should) be trusted to somehow have the vast wisdom and simultaneous omniscient grasp of countless moving, interconnected parts to micromanage an infinitely complex global monetary ecosystem. The notion is absurd and arrogant on its face. And while the Fed discusses all the factors that are causing their sticky inflation, they never seem to mention that money printing is the one dominant cause of inflation over the long term.
Rather than boiling the frog slowly, Americans have started to show a spark of awareness that inflation and rising prices are robbing them blind. Bond investors, risking trillions of dollars rather than answering opinion polls, are increasingly demanding compensation for the same inflation risk. Even the Fed has quietly acknowledged that inflation is proving more persistent than it expected, but as usual, it has backed itself into a trap.
The snare is locked, but gold is the key to the escape hatch.
Peter Schiff recently said on X:
“Bond yields rose sharply as investors lost confidence in Warsh’s actual commitment to 2% inflation. This was confirmed by gold’s resilience, as it didn’t sell off with bonds. Gold held $4K support nicely and rose on the day, reasserting its safe-haven and inflation-hedge status.”
Politicians, meanwhile, will always continue blaming each other in predictable ways for “Bidenomics” or “Trumpflation,” ignoring the inflationary constant that survives every administration: the steady expansion of the money supply and the erosion of the dollar’s purchasing power.
Americans, the bond market, and the Fed may disagree on the cause. But they are converging on the same conclusion: inflation isn’t gone. The only remaining question is how much worse it becomes before policymakers admit that the system, and policy itself, are the real problems.

QTR’s Disclaimer: Please read my full legal disclaimer on my About page here. This post represents my opinions only. In addition, please understand I am an idiot and often get things wrong and lose money. I may own or transact in any names mentioned in this piece at any time without warning. Contributor posts and aggregated posts have been hand selected by me, have not been fact checked and are the opinions of their authors. They are either submitted to QTR by their author, reprinted under a Creative Commons license with my best effort to uphold what the license asks, or with the permission of the author. I cannot guarantee the accuracy of all facts and figures included in this article though I made my best effort to get them right. I have been wrong before and will be wrong again, and encourage you to always double check, do your own research and speak to a licensed financial professional.
This is not a recommendation to buy or sell any stocks or securities, just my opinions. I often lose money on positions I trade/invest in. I may add any name mentioned in this article and sell any name mentioned in this piece at any time, without further warning. None of this is a solicitation to buy or sell securities. I may or may not own names I write about and are watching. Sometimes I’m bullish without owning things, sometimes I’m bearish and do own things. Just assume my positions could be exactly the opposite of what you think they are just in case. If I’m long I could quickly be short and vice versa. I won’t update my positions.
As of May 20, 2026 I am attempting to no longer actively trade (read my story here). My investing/saving is mostly done by recurring contributions mostly to sector ETFs and a few select equities, trusted third parties who oversee my accounts, and advisors. Such advisors or funds, through individual equities, options, index funds, mutual funds, ETFs, or other securities, may have positions in, exposure to, or holdings of names mentioned herein that I know nothing about. Basically, via index funds, ETFs and individual equities it is possible I could own, have exposure to, or not own anything at any point. As of the same date, May 20, 2026, in an attempt to lead a healthier lifestyle, I’ve also excluded myself from fantasy sports, sports betting, online and in-person casinos and prediction markets.
And all positions can change immediately as soon as I publish this, with or without notice and at any point I can be long, short or neutral on any position. You are on your own. Do not make decisions based on my blog. I exist on the fringe. If you see numbers and calculations of any sort, assume they are wrong and double check them. I failed Algebra in 8th grade and topped off my high school math accolades by getting a D- in remedial Calculus my senior year, before becoming an English major in college so I could bullshit my way through things easier.
The publisher does not guarantee the accuracy or completeness of the information provided in this page. These are not the opinions of any of my employers, partners, or associates. I did my best to be honest about my disclosures but can’t guarantee I am right; I write these posts after a couple beers sometimes. I edit after my posts are published because I’m impatient and lazy, so if you see a typo, check back in a half hour. Also, I just straight up get shit wrong a lot. I mention it twice because it’s that important.
Kevin Warsh could help by explicitly telling Congress that the Fed cannot lower inflation to 2% as long as Congress continues to pass 6-7 % deficits. The Fed must supply the money that Congress mandates be spent. By bailing out those who misallocate capital since 2008 at the expense of those who cannot afford to hold financial assets, the Fed has done incredible harm and is largely responsible for the societal inequality and discord which plagues the U.S..today. The Fed is guilty of unspeakable arrogance, but Congress is equally guilty and somehow gets a pass. Volker was not afraid to speak truth to power. Powell was. Let's see if Warsh can muster some courage.
IMHO...Based on what I see in the retail environment. Real inflation is already in double digits.